Pakistan’s new property tax rules can affect how much investors pay when buying, selling and holding real estate. Changes introduced through the 2026 tax framework include revisions to advance tax on property transactions and the removal of Section 7E, which previously taxed deemed income from certain immovable property.
For real estate investors, understanding these changes is important because taxes and transaction costs can directly affect investment returns. A property that appears profitable based only on its purchase and selling prices may produce a much smaller net return after applicable taxes and other expenses.
Key Takeaways for Property Investors
- Property transactions can involve different federal and provincial taxes and charges.
- Section 236C applies to advance tax collected on the sale or transfer of immovable property.
- Section 236K applies to advance tax collected when purchasing immovable property.
- The 2026 framework revised the advance tax rates for property transactions.
- Section 7E, which dealt with deemed income from certain immovable property, has been omitted.
- Filer status remains important when assessing property transaction costs.
- Investors should calculate the complete cost of an investment before estimating its potential return.
What Are the New Property Tax Rules?
There is no single tax that applies to every property transaction in Pakistan. The amount an investor may have to pay depends on the nature of the transaction, property value, taxpayer status and applicable federal or provincial rules.
One of the major 2026 changes concerns advance tax collected when property is bought or sold. Under the Finance Bill 2026, the rate under Section 236C, which applies to the sale or transfer of immovable property, was set at 2.75% of the gross consideration received. Section 236K, which applies to the purchase of immovable property, was set at 1.25% of the property’s fair market value.
These rates should be checked against the final applicable law and taxpayer circumstances before completing a transaction.
How Property Purchase Tax Affects Investors
Buying property involves more than the price agreed with the seller. An investor may also need to consider advance tax, registration expenses, stamp duty, transfer charges and other applicable costs.
Section 236K is particularly relevant to buyers because it covers advance income tax collected on the purchase of immovable property. The applicable calculation is linked to the fair market value of the property.
For an investor, these costs form part of the overall acquisition cost.
For example, if an investor purchases a property for investment purposes, calculating only the purchase price can give an inaccurate picture of the amount actually invested. Taxes and transfer-related expenses should be included before calculating the expected return.
What Is Section 236C Property Tax?
Section 236C concerns advance tax collected on the sale or transfer of immovable property.
Under the 2026 Finance Bill, the rate specified for Section 236C is 2.75% of the gross amount of consideration received.
This is important for investors planning to sell a property because the tax collected during the transaction can affect the cash amount received at the time of sale.
However, investors should distinguish between advance tax collected during a transaction and the final tax liability. They should not automatically treat the advance tax rate as the same thing as the overall tax on their investment profit.
What Is Section 236K Property Tax?
Section 236K applies to advance tax collected when immovable property is purchased.
The 2026 Finance Bill specifies a rate of 1.25% of the fair market value for this advance tax.
For investors, this means the property’s valuation is an important part of understanding the transaction cost. Before purchasing, buyers should determine the applicable valuation and confirm the tax amount that will be collected.
This is especially important for investors comparing several properties because additional acquisition costs can change which investment offers the better potential return.
How Do the New Rules Affect Real Estate Investors?
The impact will not be the same for every investor. Understanding how new tax reforms affect property investors can help investors assess their potential costs and returns.
A short-term investor who purchases a property and sells it after a relatively short period may be more concerned about transaction taxes and the effect of taxes on the final selling proceeds.
A long-term investor may focus more on rental income, holding costs, property appreciation and the tax treatment applicable when the property is eventually sold.
This means investors should evaluate the net return, rather than simply asking whether a property’s market value is likely to increase.
A useful calculation is:
Net investment return = Sale proceeds − purchase cost − applicable taxes − transaction expenses − other investment costs
This approach provides a more realistic picture of potential profitability.
What Changed With Section 7E?
Another important change for property owners came through the 2026 tax framework.
FBR’s 2026-27 budget documents state that Section 7E, relating to taxation of deemed income from capital assets situated in Pakistan, has been omitted.
This is relevant to investors who previously had to consider Section 7E when assessing the tax implications of holding certain immovable assets.
However, the removal of Section 7E does not mean that property ownership or transactions are completely tax-free. Other applicable federal and provincial taxes, duties, registration charges and transaction-related costs may still apply.
Investors should therefore avoid making decisions based on the assumption that one tax change eliminates all property-related liabilities.
Why Filer Status Still Matters
Taxpayer status can influence property transaction costs and should be checked before buying or selling real estate.
FBR’s property tax guidance distinguishes between different taxpayer categories for Sections 236C and 236K. The applicable treatment can depend on whether a person is a filer, late filer or non-filer, as well as the relevant property transaction.
For this reason, investors should confirm their current taxpayer status before completing a property transaction.
Maintaining proper tax records is also important for investors who regularly buy, sell or rent property.
What About Capital Gains Tax on Property?
Capital gains tax is another important consideration for anyone purchasing property with the intention of selling it at a profit.
The tax treatment can depend on factors such as when the property was acquired, the type of property, the taxpayer and the applicable provisions at the time of sale.
Investors should therefore maintain records of the original purchase price, acquisition date, improvement costs and relevant transaction expenses.
These records can help establish the actual cost of the investment and support accurate tax reporting when the property is sold.
How Rental Property Fits Into the Tax Calculation
Investors who purchase property to generate rent should consider taxation alongside rental yield.
A property may offer attractive monthly rent, but its actual return can be reduced by taxes, maintenance, vacancies, repairs, management costs and other expenses.
Therefore, investors should compare net rental income, rather than looking only at the advertised rental amount.
For example, a commercial property with a higher gross rental yield may not necessarily produce a better investment return if its operating and tax-related costs are significantly higher.
What Should Investors Check Before Buying Property?
Before making a property investment, buyers should review more than the property’s location and expected price appreciation.
A practical checklist includes:
- Current taxpayer status
- Applicable Section 236K tax
- Expected selling costs and Section 236C implications
- Capital gains tax treatment
- Property valuation
- Registration and transfer expenses
- Stamp duty and applicable provincial charges
- Expected rental income, if applicable
- Holding and maintenance costs
- Ownership and property documentation
Investors should also verify the latest tax rates and official requirements before completing a transaction because tax legislation and administrative rules can change.
How Can Investors Reduce Tax-Related Investment Risks?
The best approach is to include taxes in the investment decision from the beginning.
Instead of calculating potential profit as simply the difference between the purchase and expected selling price, investors should calculate the total acquisition cost, expected holding expenses and potential selling costs.
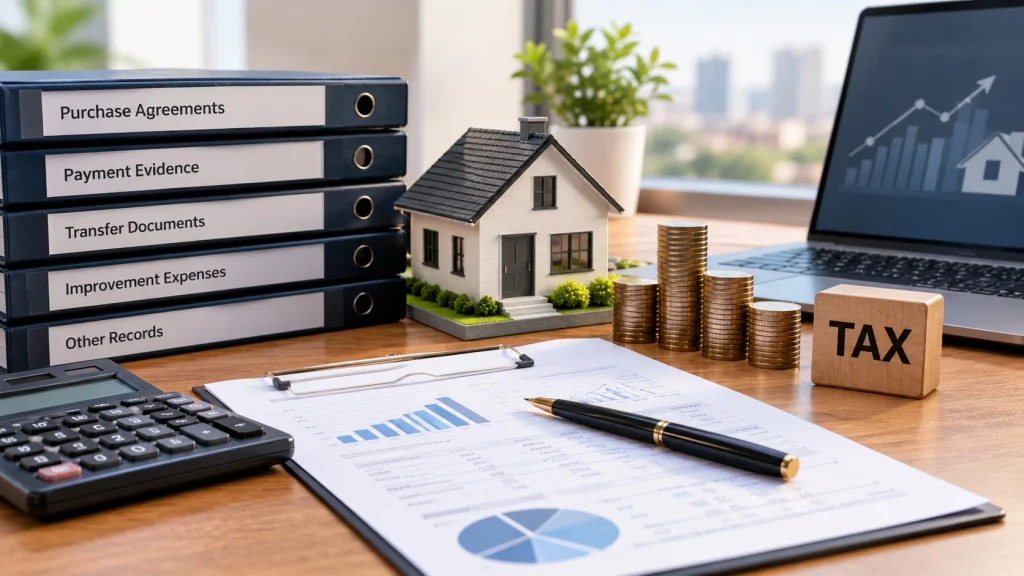
Keeping proper records is equally important. Purchase agreements, payment evidence, transfer documents, improvement expenses and other relevant records should be retained.
For significant property transactions, professional tax advice can also help investors understand their specific obligations rather than relying on general information.
Frequently Asked Questions (FAQs)
1. What are the new property tax rules in Pakistan?
The new property tax rules include changes to advance taxes on property transactions and the omission of Section 7E. Investors should check the latest applicable federal and provincial tax requirements before buying or selling property.
2. What is the property tax under Section 236K for buyers?
Section 236K applies to advance tax collected from buyers of immovable property. Under the 2026 Finance Bill, the specified rate is 1.25% of the property’s fair market value, subject to applicable rules and taxpayer status.
3. What is Section 236C property tax for sellers?
Section 236C applies to advance tax collected when immovable property is sold or transferred. The 2026 Finance Bill specifies a rate of 2.75% of the gross consideration received, subject to applicable provisions.
4. How do new property tax rules affect real estate investors?
The rules can affect an investor’s acquisition costs, selling proceeds and overall investment return. Investors should consider applicable taxes, transfer costs, capital gains tax and other expenses before calculating potential profit.
5. Has Section 7E been removed from Pakistan’s property tax system?
Yes. The 2026 tax framework omitted Section 7E, which previously concerned deemed income from certain immovable property. However, other property-related taxes, duties and transaction charges may still apply.
Conclusion
The new property tax rules make tax planning an important part of real estate investment in Pakistan. Changes to advance tax under Sections 236C and 236K and the omission of Section 7E can affect how investors assess the cost of buying, selling and holding property.
The key lesson for investors is simple: do not calculate property profitability from price appreciation alone.
Before investing, consider the purchase price, applicable taxes, transfer costs, potential capital gains tax, rental income and ongoing expenses. Checking these factors in advance can help investors understand their true potential return and make more informed property decisions.


